What Is Blockchain and Why It Matters
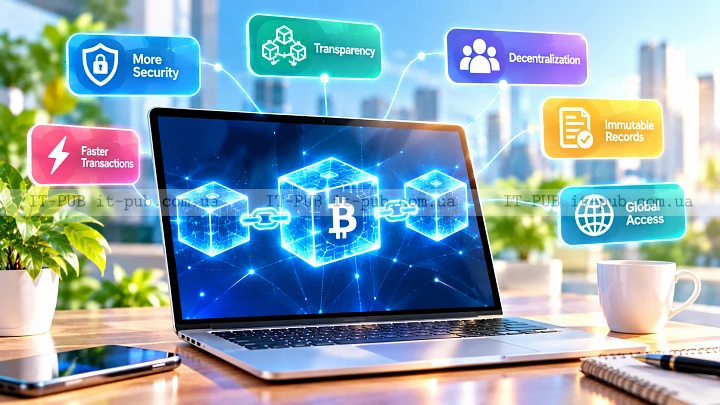
What is blockchain, and why does it come up so often in tech discussions? In simple terms, it is a way to store and share information so multiple computers keep the same record at once. That setup makes the record easier to verify and much harder to quietly tamper with.
It may sound technical at first, but the core idea is pretty straightforward. Think of a shared notebook that many people can read, while no one can secretly erase or rewrite past entries. If that makes sense, you already have a solid starting point for blockchain explained simply.
Blockchain in simple terms
A blockchain is a digital ledger. A ledger is just a record of transactions or events. In a traditional setup, that record usually sits under the control of one organization in one place. A bank keeps account balances. A company stores shipment records. A government system maintains property data.
Blockchain technology works in a different way. Instead of one central database controlling everything, the record is shared across a network of computers. Each computer holds a copy of the same data. When new information is added, the network checks it before the shared record is updated.
That is why people describe blockchain as decentralized. No single computer, person, or server fully controls the entire record. Trust is spread across participants in the network rather than handed to one central owner.
Why the word “blockchain” matters
The name describes how the data is arranged. Information is grouped into blocks. Each block contains a set of records, and every new block connects to the one before it. Over time, those connected blocks form a chain.
That structure matters because it makes the record difficult to change without being noticed. If someone alters one block, the connection to the blocks after it no longer matches. In a well-designed decentralized network, other computers can detect that mismatch.
That does not make blockchain magical, and it does not mean attacks are impossible. It means the system is built so unauthorized changes are difficult and visible.
How blockchain works step by step
The easiest way to understand how blockchain works is to break it into a few stages.
Someone creates a transaction or record. That could be a payment, a transfer, or another kind of digital event.
The transaction is then sent to the network. Many computers, often called nodes, receive it and check whether it follows the rules.
Verified transactions are grouped into a block. Once that block is accepted, it is added to the chain in a fixed order.
After that, the updated distributed ledger is shared across the network, so participants have the same version of the record.
That shared verification is the key idea. Instead of relying only on one central authority, the system depends on many computers agreeing on the same data.
Why blockchain is hard to alter
One of the best-known features of blockchain is immutability. In plain English, that means records are very hard to change after they are added. It does not mean corrections are impossible in practice, but it does mean the original record remains visible and changes are not easy to hide.
The reason comes from the structure itself. Each block is tied to the one before it. Change one block, and the chain no longer lines up properly. The network can reject that altered version.
This matters anywhere a reliable history is important. It can help with tracking ownership, verifying transactions, or keeping a clear trail of events. In many cases, the value of blockchain is not speed. It is trust, traceability, and shared verification.
Blockchain and decentralization
Decentralization is one of the words most closely tied to blockchain. Put simply, it means control is spread out instead of being concentrated in one place.
That can reduce reliance on a single point of failure. If one server goes offline, the whole system does not automatically stop. If one party tries to change the record on its own, the rest of the network can reject that change.
Still, blockchain is not automatically better than a traditional database. Centralized systems are often faster, simpler, and cheaper to run. Blockchain makes sense when several parties need the same trusted record and do not want one participant to control it alone.
Where blockchain is used
Blockchain technology is most closely associated with digital money, but its uses go beyond that. It can support systems where tracking, verification, and shared records matter.
One of the most familiar blockchain examples is cryptocurrency. In that case, the blockchain records transfers between users. The network helps confirm that a transaction is valid and has not already been used somewhere else.
Blockchain can also be used in supply chains. A company may want to track where a product came from, where it moved, and when it changed hands. A shared ledger can make that history easier to inspect.
Another possible use is digital identity. Rather than storing every piece of identity data in one central location, a system may use blockchain-related methods to verify certain details more securely.
It can also support record-keeping for assets, certificates, or contracts where a clear audit trail matters. The exact design depends on the problem being solved.
What blockchain is good at
Blockchain is not the right tool for every job, but it does handle some problems well.
It is especially useful when several parties need one shared version of the truth. It also helps when records need to stay traceable over time. Because entries are linked and checked by the network, the history is easier to audit.
In some systems, transparency is another advantage. Depending on how the blockchain is designed, participants may be able to inspect records and confirm what happened without asking one central operator for access.
At the same time, transparency does not always mean everything is public. Some blockchains are open to anyone. Others are built for private or limited groups. The structure can vary a lot.
Common misconceptions about blockchain
A lot of people hear the word blockchain and assume it means cryptocurrency. That is not correct. Cryptocurrency can use blockchain, but blockchain itself is a broader way of recording data.
Another common misunderstanding is that blockchain removes the need for trust. It does not. You still have to trust the network’s rules, the software, and the people building the system. Blockchain changes where trust sits; it does not make trust disappear.
Some people also assume blockchain is always the best answer for security. In reality, security depends on the whole system, not just the ledger. If users lose access to their accounts or an app is badly built, blockchain will not solve those problems on its own.
There is also a belief that blockchain is always public and anonymous. In practice, some networks are public, some are private, and privacy levels vary. In many cases, blockchain data can be traced more easily than people expect.
Blockchain versus a regular database
A regular database is often the better choice when one organization controls the data and needs fast updates. It is simpler to maintain and easier to scale for many everyday business tasks.
Blockchain makes more sense when multiple independent parties need to share records without giving one central owner complete control. It is particularly useful when the history of changes matters just as much as the current state.
A database can usually be edited more easily. Blockchain is built to make edits difficult and visible. That trade-off is part of the design, not a flaw.
So the choice is not really “blockchain or database” in the abstract. It depends on who needs the data, who controls it, and how much the parties trust one another.
What beginners should remember
If you want the shortest useful answer to what is blockchain, it is this: a shared digital record maintained by many computers together. Information is stored in blocks, and those blocks are linked in order. Because the network checks new entries, the record is difficult to change without detection.
That is the core idea. Everything else grows from it.
For beginners, the most helpful way to think about blockchain is not as a trendy label but as a system for shared verification. It is a way to keep a history that multiple participants can trust, even if they do not fully trust each other.
Why businesses and developers care
Businesses pay attention to blockchain when they need stronger traceability, coordination across multiple parties, or a dependable audit trail. Developers look at it when they want applications built around shared records instead of one central database.
That said, blockchain is not a universal fix. It can add complexity. It may be slower than traditional systems. It can be harder to change or maintain. Sometimes those trade-offs are worth it. Sometimes they are not.
That is why good technical decisions start with the problem itself, not the buzzword. If the real need is a shared, tamper-resistant record, blockchain may be a good fit. If not, a standard database may do the job better.
A practical way to think about it
Imagine several organizations keeping the same logbook. Each has its own copy. Before a new entry is added, the group checks that it is valid. Once accepted, the entry becomes part of the permanent record, and everyone updates their version.
That is the basic logic behind blockchain.
It is not about sending data into some mysterious black box. It is about making records harder to alter, easier to verify, and shared across a distributed ledger instead of locked inside one system.
That is why blockchain still matters. Not because it sounds futuristic, but because it helps solve a real coordination problem. When trust, traceability, and shared control matter, it offers a different way to build digital systems.